


The Cost of a Bad Credit Score
Some of life’s biggest moments are also some the most expensive. The average cost of a home in the U.S. is more than $300,000. A college degree can easily top $100,000. Even the price of new car can exceed $30,000.
The average person can save thousands throughout their lifetime by maintaining a good credit score. It can knock down the interest rate on a car by 10 percent and cut the amount a person pays in interest for a college degree in half. Maintaining a good credit score can also keep you from joining the 1 in 10 unemployed people who are denied a job due to poor credit.
“When most people think about bad credit scores they think about their impact on the ability to borrow but one thing they don’t think about is the impact on their careers,” said MaryAnn Monforte, professor of accounting practice at Syracuse University’s Whitman School of Management. “Prospective employers will check credit history, particularly in the finance and insurance industries. How well you manage your finances, including your credit score, can be an indication of how well you will perform on the job.”
This is why it’s important to understand what goes into maintaining a good credit score and to know exactly what your current credit score is.
What Is a Credit Score?
A credit score is a numerical rating from 300 to 850 that expresses how much of a potential risk you may be to lenders. Simply put: A low number means you are a risky investment.
While companies define their risk categories differently, the range tends to look something like this:
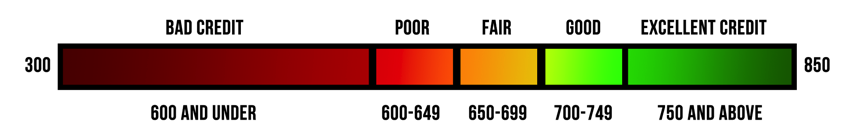
Bad Credit: 600 and Under | Poor: 600-649 | Fair: 650-699 | Good: 700-749 |Excellent: 750 and Above
Having a credit score that falls on the lower end of the spectrum can result in being denied loans and even leases on apartments. A bad credit score is not only inconvenient, it is also expensive. Even if you’re approved for a loan, your interest rate is determined in large part by your credit score.
How Is a Credit Score Calculated?
A credit score is based on your credit report information, usually from the three most prominent credit bureaus in the United States: TransUnion, Equifax and Experian. The most common calculation of a credit score is through the FICO method, which uses the following five factors to determine a score.
- Payment history — 35 percent: Often the most important part of your credit score, payment history tells lenders if you have a history of paying your debts on time.
- Amounts owed — 30 percent: A high amount owed is not necessarily a bad influence on credit. FICO looks at your “Credit Utilization Ratio,” which is the percentage of your available credit that is currently being used. For example, if your credit card sets your credit limit at $1,500 and you keep a balance of $1,400, you may be at risk of negatively affecting your credit score.
- Length of credit history — 15 percent: In general, the longer your credit history, the better. For those just starting to build a credit history, don’t worry. It is still possible to maintain a high credit score by paying extra attention to the other criteria.
- Credit mix in use — 10 percent: The credit mix looks into the types and number of credit accounts owned. While it is a good idea to maintain credit accounts, it is not a good idea to open an account you don’t intend to use.
- New credit — 10 percent: Opening multiple new lines of credit in quick succession can negatively affect a credit score. Despite myths about credit inquiries being harmful, these alone tend to have little to no effect.
Keep in mind that your credit score is just one factor lenders consider. They will likely look into your income, debt-to-income (DTI) ratio, and length of employment in addition to your credit score before issuing a line of credit.
How Do I Find My Credit Score?
You’re entitled to one free credit report per bureau every 12 months, but in order to get your credit score you’ll most likely have to pay a fee. Certain banks offer free credit scores with memberships. You can purchase your score directly from FICO, or find a credit report monitoring service you like and purchase a subscription to get your credit score included for free.
It is important to monitor your credit report and immediately dispute any fraudulent or incorrect information. The Federal Trade Commission lays out that process here.
If you have a checkered credit history, fixing a bad credit score is possible, but it is a lengthy process. FICO provides a list of tips for repairing a credit score. The most important word for those working to improve their scores is “patience.”
Why Is My Credit Score Important?
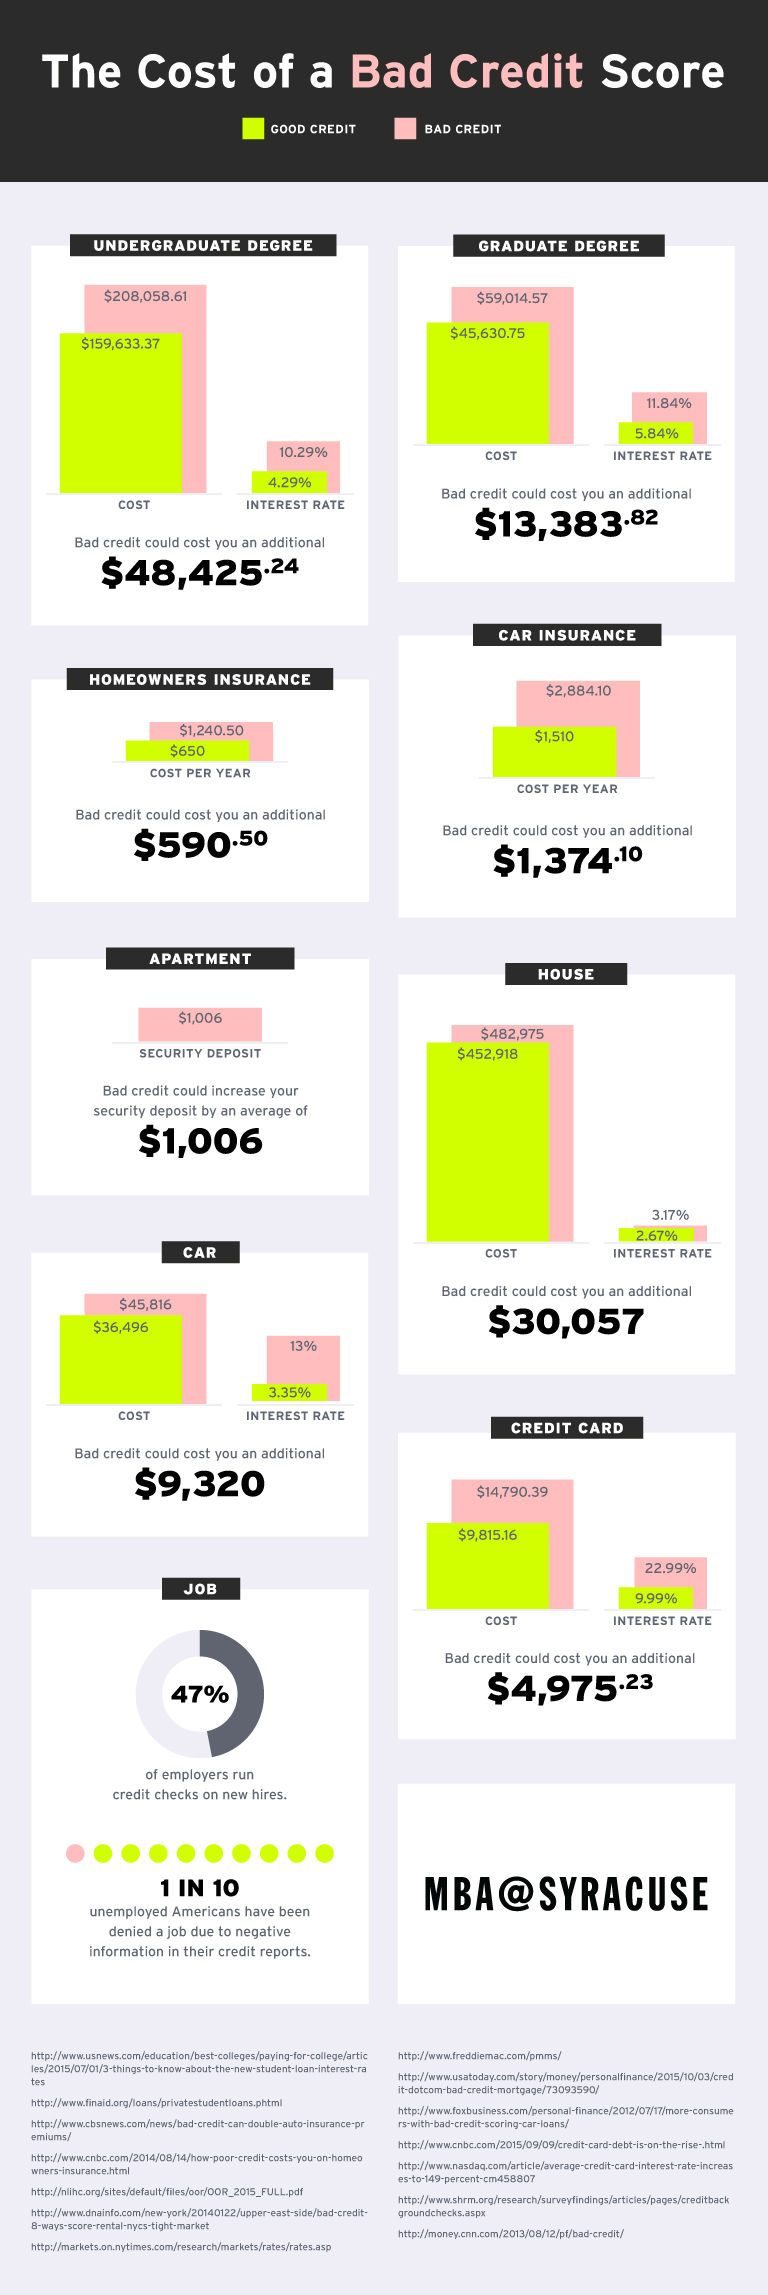
Your credit score impacts milestone purchases. When the time comes to go back to school or buy that dream home, you don’t want your credit score standing in your way. In case you’re not convinced yet, we’ve calculated some of the expected costs and consequences of a bad credit score over a lifetime. While it’s hard to pin down the exact cost of many of these purchases, these are good estimates. The interest rates are from January 2016 and the costs are 2015 national averages. Looking at how quickly these costs build up, it’s easy to see why it’s worth spending time on your credit score now, rather than spending money on it later.
-
Undergraduate Degree
Cost
Good Credit: $159,633.37
Bad Credit: $208,058.61
Interest Rate
Good Credit: 4.29%
Bad Credit: 10.29%
Bad credit could cost you an additional $48,425.24.
Graduate Degree:
Cost
Good Credit: $45,630.75
Bad Credit: $59,014.57
Interest Rate
Good Credit: 5.84%
Bad Credit: 11.84%
Bad credit could cost you an additional $13,383.82.
Homeowners Insurance
Cost Per Year
Good Credit: $650
Bad Credit: $1,240.50
Bad credit could cost you an additional $590.50.
Car Insurance
Cost Per Year
Good Credit: $1,510
Bad Credit: $2,884.10
Bad credit could cost you an additional $1,374.10.
Apartment
Security Deposit
Bad Credit: $1,006
Bad credit could increase your security deposit by an average of $1,006.
House
Cost
Good Credit: $452,918
Bad Credit: $482,975
Interest Rate
Good Credit: 2.67%
Bad Credit: 3.17%
Bad credit could cost you an additional $30,057.
Car
Cost
Good Credit: $36,496
Bad Credit: $45,816
Interest Rate
Good Credit: 3.35%
Bad Credit: 13%
Bad credit could cost you an additional $9,320.
Credit Card
Cost
Good Credit: $9,815.16
Bad Credit: $14,790.39
Interest Rate
Good Credit: 9.99%
Bad Credit: 22.99%
Bad credit could cost you an additional $4,975.23.
Job
47% of employers run credit checks on their new hires.
1 in 10 unemployed americans have been denied a job due to negative information in their credit reports.
MBA@Syracuse
Sources
http://www.usnews.com/education/best-colleges/paying-for-college/articles/2015/07/01/3-things-to-know-about-the-new-student-loan-interest-rates
http://www.finaid.org/loans/privatestudentloans.phtml
http://www.cbsnews.com/news/bad-credit-can-double-auto-insurance-premiums/
http://nlihc.org/sites/default/files/oor/OOR_2015_FULL.pdf
https://www.dnainfo.com/new-york/20140122/upper-east-side/bad-credit-8-ways-score-rental-nycs-tight-market
http://markets.on.nytimes.com/research/markets/rates/rates.asp
http://www.freddiemac.com/pmms/
http://www.usatoday.com/story/money/personalfinance/2015/10/03/credit-dotcom-bad-credit-mortgage/73093590/
http://www.foxbusiness.com/features/2012/07/17/more-consumers-with-bad-credit-scoring-car-loans.html
http://www.cnbc.com/2015/09/09/credit-card-debt-is-on-the-rise-.html
http://www.nasdaq.com/article/average-credit-card-interest-rate-increases-to-149-percent-cm458807
https://www.shrm.org/hr-today/trends-and-forecasting/research-and-surveys/pages/creditbackgroundchecks.aspx
http://money.cnn.com/2013/08/12/pf/bad-credit/